
The Private Credit Market Boom ($41 Trillion Market): Transforming Global Corporate Finance
The global financial landscape is undergoing a monumental shift. For decades, traditional commercial banks held an absolute monopoly over corporate lending, acting as the primary gatekeepers of capital for businesses scaling up or restructuring. However, stringent regulatory compliance, tightening monetary policies, and post-crisis capital requirements have forced traditional banks to step back. Enter the alternative lending ecosystem—ushering in an unprecedented The Private Credit Market Boom ($41 Trillion Market) that is redefining how modern corporations secure liquidity and long-term funding.
Why Traditional Banks Are Retreating and Making Room for Private Debt
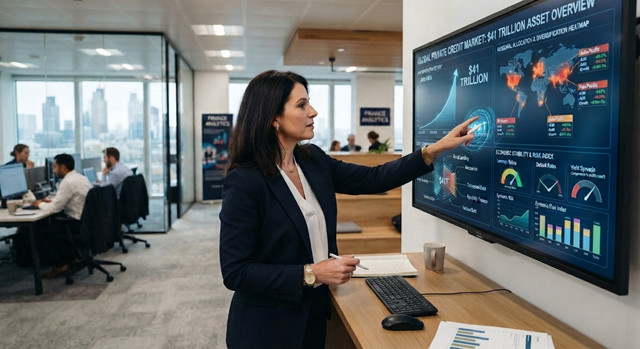
To fully understand The Private Credit Market Boom ($41 Trillion Market), we must first examine the structural constraints facing conventional financial institutions. Regulatory frameworks such as Basel III and subsequent tightening measures have made balance-sheet lending highly capital-intensive for commercial banks. Consequently, banks are far more selective, favoring ultra-safe corporate borrowers and leaving mid-sized, high-growth, or restructuring companies struggling to secure capital through legacy channels.
This funding vacuum created an ideal environment for non-bank financial intermediaries, private equity asset managers, and specialized direct lending funds. Offering high flexibility, speed of execution, and customized loan structuring, these private credit providers stepped in seamlessly. Companies requiring rapid capital injection no longer face months of bureaucratic red tape. Instead, they partner directly with private institutional lenders who can underwrite multi-million-dollar loans in a fraction of the time.
The Structural Mechanics Driving the $41 Trillion Expansion
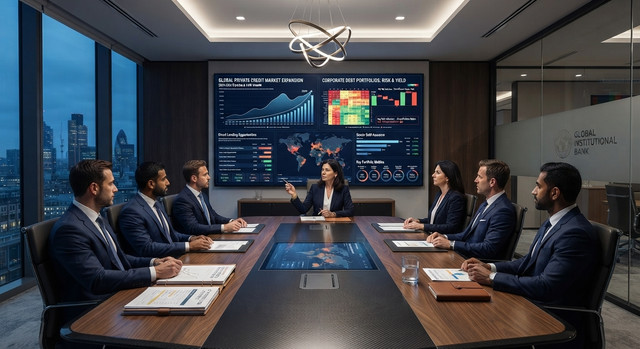
The sheer velocity of capital accumulation within alternative assets is staggering. Institutional investors—including pension funds, insurance companies, and sovereign wealth funds—are actively reallocating fixed-income portfolios toward private credit to chase superior risk-adjusted yields in an era of persistent macroeconomic volatility. As public debt markets fluctuate under the weight of shifting interest rates, private credit provides predictable, floating-rate returns that protect institutional portfolios against inflationary pressures.
Furthermore, middle-market enterprises find immense value in dealing with a single private lender rather than managing a complex syndicated loan arrangement distributed among dozens of public bondholders. This confidential, bilateral relationship allows companies to execute strategic acquisitions, weather short-term cash flow crunches, and fund capital expenditures without the intense public scrutiny associated with public debt issuance.

Evaluating the Hidden Risks Within The Private Credit Market Boom ($41 Trillion Market)
Despite its remarkable ascent, rapid expansion brings structural vulnerabilities. Financial regulators across the US and UK have voiced growing concerns regarding transparency, liquidity mismatches, and valuation practices within private credit funds. Because these loans are rarely traded on public exchanges, valuing them accurately requires complex internal models rather than transparent market pricing.
Additionally, as interest rates remain elevated, corporate borrowers face heightened debt-servicing burdens. While private credit lenders often implement robust covenants and monitoring structures, an extended economic downturn could test portfolio resilience, leading to elevated default rates and delayed restructuring processes. Investors and market participants must maintain rigorous risk assessment standards to navigate potential liquidity bottlenecks.
Conclusion: The Future Outlook for Global Borrowers and Lenders
In summary, The Private Credit Market Boom ($41 Trillion Market) is far more than a temporary market trend; it represents a permanent structural evolution in global corporate finance. As traditional banks continue to manage strict capital reserves, alternative lending will remain a vital engine for economic growth, business expansion, and liquidity management. However, balancing aggressive yield-seeking behavior with prudent risk management will determine the long-term stability and success of this booming asset class.



0 Comments